Skip to content

PoliticsCalifornia5 min read

California Billionaire Tax: Page, Ellison Make Strategic Moves

California's proposed 2026 Billionaire Tax has prominent figures like Larry Page and Larry Ellison making 'strategic moves.' Learn the details.

Share

Topics

California billionaire tax debate fuels strategic moves: Larry Page shifts companies, Larry Ellison sells San Francisco home

California’s proposed 2026 Billionaire Tax Act would impose a one‑time 5% tax on residents with $1 billion+ in worldwide net worth, prompting reported residency and corporate moves by figures like Larry Page and Larry Ellison amid legal and fiscal uncertainty.
  • What the measure would do: A one‑time 5% levy on worldwide net worth for residents worth $1 billion or more, measured Dec. 31, 2026, with collections beginning in 2027.
  • Reported responses: Media reports say some billionaires are re‑domiciling entities or selling property — notably moves tied in reporting to Fox Business coverage.
  • Fiscal and legal uncertainty: Estimates vary; the measure could raise tens of billions but faces likely court challenges and behavioral responses that affect revenue.

Overview

The proposed 2026 Billionaire Tax Act would amend the state constitution to assess a one‑time 5% tax on the worldwide net worth of any California resident (or part‑year resident on Jan. 1, 2026) with at least $1 billion in net worth on Dec. 31, 2026. Proponents say the revenue would fund Medi‑Cal, K–14 public education and food support.

What the proposal would do

  • Base and rate: One‑time 5% on worldwide net worth above the $1 billion threshold, measured at year‑end 2026.
  • Payment timing: Collections would begin in 2027; taxes may be paid over five years with charges for deferral.
  • Funding purposes: Dedicated state fund for health care (Medi‑Cal), K–14 education and food assistance programs.

Sources for the proposal text and analyses include the Initiative text and a revenue analysis.

How the tax is calculated and paid

The tax base reaches into worldwide assets and property interests of taxpayers and their spouses, minus certain debts. That includes ownership stakes in businesses, stocks, bonds, art, intellectual property and other items. Certain items are generally excluded or partially exempt — for example, directly held California real estate, some retirement accounts and tangible property kept outside California for much of 2026. Legal summaries and counsel commentary detail exclusions and apportionment rules; see a summary by Baker Botts.

Who would be covered and timing

Anyone who is a California resident — or a part‑year resident on Jan. 1, 2026 — and has at least $1 billion in worldwide net worth on Dec. 31, 2026 would be subject to the levy. Moving after Jan. 1, 2026 likely would not avoid liability under the plain text of the proposal; valuation and residency dates are key.

Reported billionaire moves — what’s public and what’s inferred

Larry Page and corporate re‑domiciling

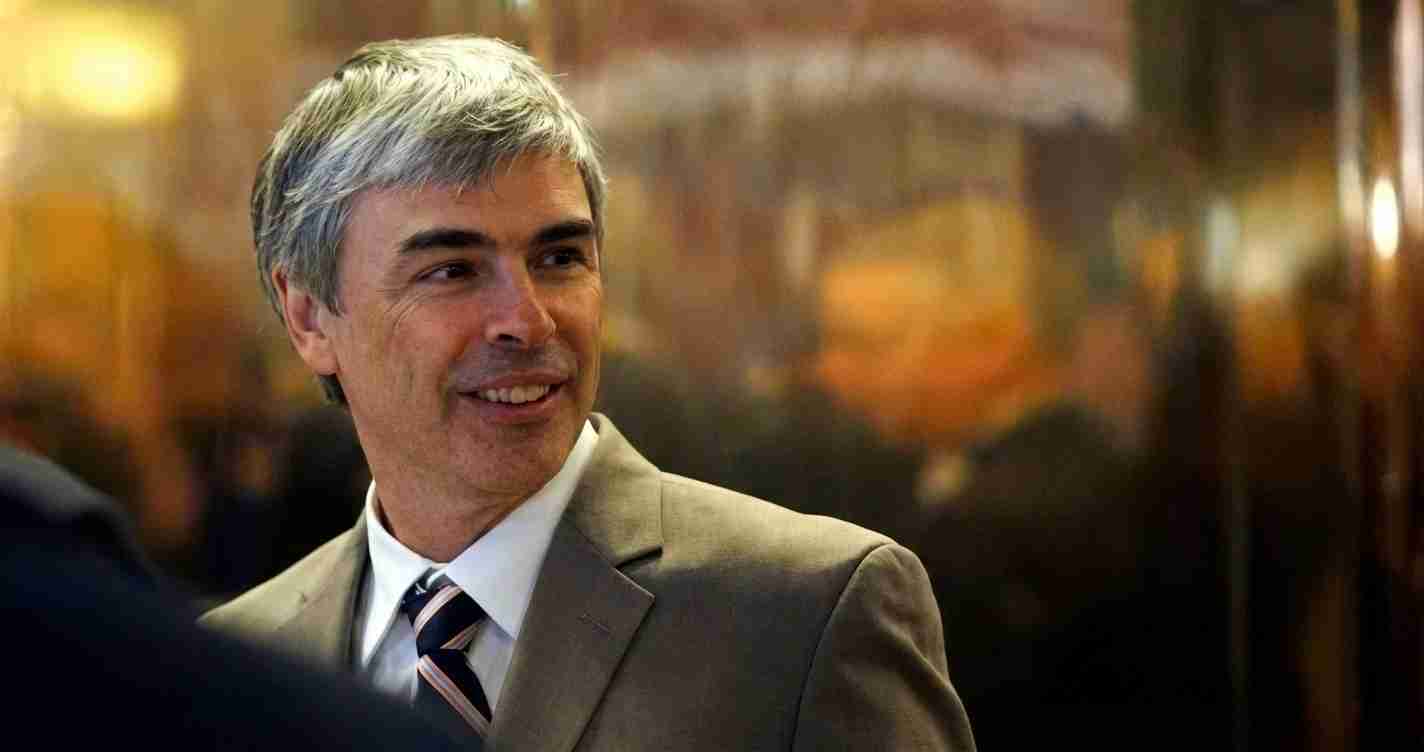
Recent reporting indicates Google co‑founder Larry Page has taken steps to re‑domicile some business entities to Delaware and Florida. Changing corporate domicile can alter governance and the legal situs of assets, but the proposed tax targets individual residency and worldwide net worth; corporate domicile alone does not automatically erase personal tax exposure if the individual remains a California resident. Reporting on Page’s actions appears in Fox Business.

Larry Ellison and San Francisco property

Reports say Larry Ellison sold a San Francisco home for roughly $45 million. Because directly held California real estate is generally excluded from the measure’s base, the sale may reflect broader residency changes rather than merely removing that property from the tax calculation. Those reports are documented in Fox Business and summarized in an explainer by CBS News.

Note: Media reports link timing and actions but do not include direct admissions from the people named that the proposed wealth tax was the sole motive.

To reach the November 2026 ballot, proponents must collect about 875,000 valid signatures. If approved by voters, the measure would likely face immediate legal challenges. Critics point to California’s constitutional limits on some property tax rates and raise concerns about targeting a small group, interstate commerce, and due process. Supporters counter that the tax addresses concentrated wealth and would fund key public services. Legal commentary and scenarios are summarized by Baker Botts.

Why relocation may not easily avoid the tax

Experts note the proposal measures residency at a specific date and values at year‑end, so timing is crucial. Moving corporate entities or re‑domiciling companies can change where assets sit legally, but they do not by themselves change an individual’s residency. The state could apply apportionment rules and audits to capture wealth tied to California. See analysis by UC Berkeley economists and others for revenue and behavioral assumptions (revenue study).

Implications for Fresno, California

  • Local services and budgets: If implemented, the dedicated fund could channel state dollars to Medi‑Cal, K–14 education and food programs that benefit Fresno schools, community colleges and health providers.
  • Risk to longer‑term support: If wealthy residents or investment shift out of California, future income and capital gains receipts could decline, tightening state budgets that Fresno relies on.
  • Jobs and investment: Fresno’s economy — focused on agriculture, health care and education — could gain from expanded public funding but lose private philanthropy or venture ties if ultra‑wealthy donors reduce engagement.
  • Housing markets: Changes in ultra‑high‑end Bay Area activity have limited direct effect on Fresno housing, but state funding changes and broader economic shifts could affect local housing programs.

Reporting notes and sources

This article draws on the proposed initiative text filed with the California Attorney General, reporting from CBS News and Fox Business, a revenue study by economists at UC Berkeley and others, and summaries from legal and tax advisers.
Note: Media reports linking individual moves to the proposed tax describe timing and corporate or real estate actions but do not include direct admissions from those named that the wealth‑tax proposal is the sole motive. Legal and fiscal outcomes remain uncertain and will depend on signature gathering, voter approval, and likely court challenges.

Share

Topics

Joel Patterson

Joel Patterson is a senior business and finance analyst for Times Media Service, based in the Washington bureau. Patterson covers markets, companies, personal finance and economic policy, along with transportation and its financial and economic impacts. Patterson holds a master's degree in finance and grew up in Newcastle upon Tyne, England.

Write to Joel